
We’re often asked how we whittle down the vast universe of public equities into a workable list that fits DM’s investment criteria and warrants further investigation. The first step in this funneling process involves screening stocks against a set of “gating factors” to eliminate names which don’t match our core principles of cash flow generation, growth, and effective redeployment. The first of our screens is industry outlook, or whether the company is operating in a part of the economy which is both expanding and likely to maintain its favourable profile into the foreseeable future.
Our decision to add shares of aircraft parts maker, HEICO Corp., to DM US Equity in early 2025 was underpinned not only by very strong industry fundamentals, but also by a regulatory structure that presents substantial barriers to competition. Not surprisingly, the certification process required to make replacement parts for commercial airplanes is extremely demanding, which severely impedes entrants to the space and greatly enhances the pricing power of incumbents. At the same time, travel activity has been on a steady climb in recent years:
- In 2025, travel & tourism was one of the world’s fastest growing sectors, outpacing the aggregate economy by nearly 50%;
- American trips to Europe jumped from about 17.5m annually before covid to 24m in 2025;
- In 2005, about 22% of Americans held a passport, while today that figure is roughly 55%.
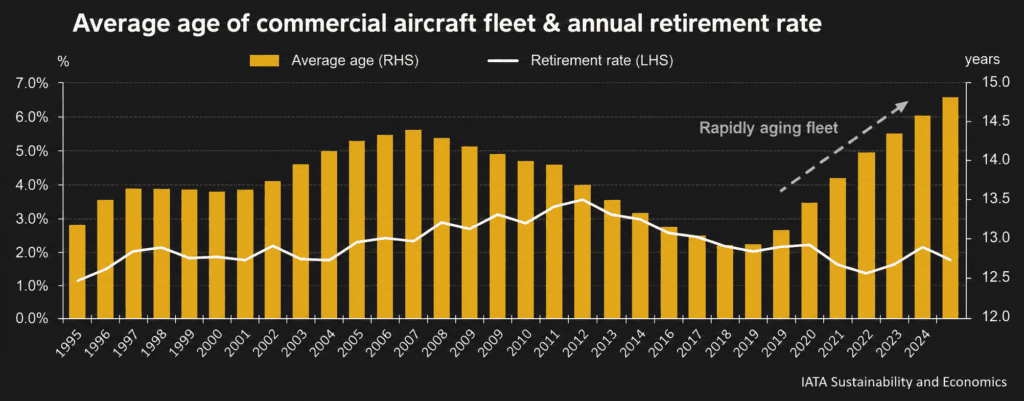
This persistent rise in travel demand, coupled with large order backlogs at the major aircraft makers, has forced airlines to keep planes in the air longer, leading to a record average fleet age (see chart); of course, when elevated flight activity collides with historically old planes, maintenance requirements and the need for replacement parts naturally increase.
Since our initial purchase of HEICO, the stock has outperformed the S&P 500 by about 15% and we’re comfortable that its runway for future growth remains attractive. In fact, to boost our exposure to the well-positioned sector, we recently added shares of TransDigm Group, another maker of aftermarket engineered aircraft components.
Portfolio Activity
Through the summer, we made several rebalancing trades in DM equity mandates, primarily aimed at reducing risk in positions which had appreciated beyond our fundamental value estimates and adding to names which we believe offer compelling upside.
Feature Stock
Roper Technologies Inc. (ROP)
ROP designs and develops vertical software and technology enabled products for a variety of niche markets, including legal, education, healthcare admin., property mgmt., and government contracting. Like many names in the software space, however, ROP shares slumped in the opening weeks of 2026 on the premise that AI tools could replicate the company’s products and undermine its market position. In reality, though, the barriers to replacing ROP in a user’s tech stack will likely prove much more difficult than investors initially surmised, owing to the decades of data that many of its business lines have accumulated, the regulatory certifications required by many of its functions, and the workflow integration that ROP products help to enable. The durability of its portfolio was reflected in Q2 earnings, which showed a high rate of customer retention alongside a profit jump of 11%; during the quarter, ROP also bought back $1.2bn in stock, bringing cumulative repurchases to 8% of outstanding shares over the past 9 months. Since early June, ROP shares have gained about 30%.